 Points

If you've lived in the Okanagan long enough, you've seen it: sandbags stacked along Lakeshore Road, beaches disappearing under grey water, and neighbours in rubber boots helping each other move furniture up from the basement. Flooding is part of this valley's story — and it has been for well over a century.
But here's something many property owners don't realize until they're standing in ankle-deep water: not all floods are treated the same. Water that rises up from the lake or rushes down a hillside is handled very differently — by both restoration professionals and insurance companies — than water that bursts out of a pipe inside your home.
Let's look at the valley's flood history first, and then break down why the source of the water matters so much when it's time to clean up and file a claim.
A Valley Shaped by Water
The Okanagan has always flooded. Long before dams and dikes, Okanagan Lake rose and fell dramatically with the spring freshet — the annual surge of melting snow from the surrounding highlands. Early surveys pegged the highest recorded natural lake level at roughly 343.7 metres back in 1904, with reports of even higher water in the 1890s.
The mid-20th century brought the events that reshaped how the valley manages water. After serious flooding in 1948 — the same year as the devastating Fraser Valley flood — pressure mounted for a permanent solution. By 1951, snowpack in the region's mountains hit 140 per cent of normal, and local newspapers warned the flood situation could be worse than 1948. In one dramatic episode that spring, a section of Highway 97 north of Oliver had to be blasted out just to release spring runoff, because the culverts couldn't handle the flow.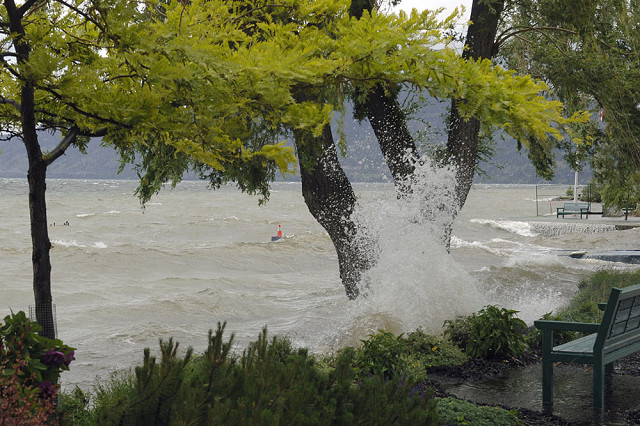
The result was the Okanagan Flood Control Project, a joint federal-provincial undertaking built between 1950 and 1958. It channelized and diked the Okanagan River, added drop structures between the lakes, and created the regulation system — including the now-iconic Penticton channel — that still manages lake levels today.
For decades, that system largely did its job. Then came 2017.
2017 and 2018: The Modern Wake-Up Call
In 2017, a perfect storm of late-season snow accumulation, heavy rain, and rapid melt drove Okanagan Lake to its highest level ever recorded — 343.251 metres on June 9, 2017, roughly 77 centimetres above full pool. Waves pounded lakeshore defences in Kelowna, states of emergency were declared, creeks like Mill Creek jumped their banks, and residents waded through knee-deep water to protect their homes and help their neighbours.
Then it happened again. The 2018 freshet generated flows comparable to 2017, pushing the lake about 20 centimetres over full pool and causing renewed erosion and sediment movement in local creeks — though improved channel maintenance meant far less damage the second time around.
Those back-to-back years prompted a major rethink. The Okanagan Basin Water Board, local governments, and the Okanagan Nation Alliance commissioned updated floodplain mapping for the entire valley. The findings weren't comforting: with warmer temperatures, more rain, less snow, and earlier freshets, peak lake levels could rise further in the decades ahead, and flood forecasting will only get harder. For Okanagan and Kalamalka lakes, the 2017 flood is now used as the benchmark "design flood" for planning purposes.
The takeaway for property owners is simple: overland flooding isn't a once-in-a-lifetime event here. It's a recurring feature of life in this valley — and one that's expected to intensify.
Two Kinds of Floods, Two Very Different Situations
When water damages your home, the first question a restoration professional — and your insurance adjuster — will ask is: where did the water come from?
Overland flooding is water that starts outside and comes in: a rising lake, an overflowing creek, torrential rain pooling against your foundation, rapid snowmelt, or runoff racing down a burn-scarred hillside. It enters at ground level through doors, window wells, foundation cracks, and low openings.
Internal (sudden and accidental) water damage starts inside your home: a burst supply line, a failed hot water tank, an overflowing washing machine, a leaking dishwasher, or a ruptured pipe in the wall.
They can leave a basement looking equally soaked — but from there, the two situations diverge sharply.
How Restoration Differs
Overland flood water is contaminated water
In the restoration industry, water is categorized by contamination level. Water from a burst supply line is typically "clean" (Category 1) when the loss occurs. Overland flood water is the opposite end of the spectrum — Category 3, often called "black water." It has travelled across roads, lawns, agricultural land, and storm systems, picking up silt, sewage, fuel, pesticides, bacteria, and debris along the way.
That changes everything about the restoration approach:
- More material has to go. Porous materials soaked by clean water — carpet, drywall, insulation — can sometimes be dried and saved if crews respond quickly. Materials saturated with contaminated flood water generally must be removed and disposed of, because no amount of drying makes them sanitary again.
- Decontamination is mandatory. Flood restoration involves anti-microbial treatment of the structure, not just drying. Silt and sediment must be flushed from wall cavities, ducting, and mechanical systems.
- Safety protocols are stricter. Crews work in personal protective equipment, and homeowners are advised to avoid contact with flood water and anything it touched.
- The timeline is longer. Flood events also tend to be community-wide, meaning equipment, trades, and adjusters are stretched thin at exactly the moment everyone needs them.
Internal water damage rewards speed
With a clean-water loss like a burst pipe, the clock is the enemy — but it's also your friend. If mitigation starts within the first 24 to 48 hours, structural drying can often save flooring, drywall, and contents that would otherwise be lost, and prevent the loss from escalating into a mould problem. The work is more about rapid extraction, targeted demolition, and controlled drying than about decontamination.
Either way, the golden rule is the same: call a restoration professional immediately. The difference is that with overland flooding, you may also be coordinating with your municipality, emergency programs, and a much busier insurance system.
How Insurance Differs — And Why This Catches People Off Guard
This is where many Okanagan homeowners get an unwelcome surprise.
Internal water damage: usually covered
Standard home insurance policies in Canada typically cover sudden and accidental water damage from sources inside the home — burst pipes, ruptured heating systems, leaking appliances, and failed hot water tanks. If your washing machine hose lets go while you're at work, you're generally dealing with a covered loss (subject to your policy wording and deductible).
Overland flooding: only covered if you've added it
Here's the critical part: coverage for overland flooding is not typically included in a standard home insurance policy. For most of Canadian insurance history, you simply couldn't buy it at all — overland flood coverage only became widely available as an optional endorsement after the catastrophic floods of 2013.
Overland water coverage is an optional add-on that typically protects against fresh water entering your home from heavy rainfall, rapid snowmelt, or the sudden rise of a lake, river, or creek. A few things every valley property owner should understand:
- You have to ask for it. If you've never specifically discussed overland water coverage with your broker, there's a good chance you don't have it.
- It's separate from sewer backup coverage. Water backing up through drains, sewers, septic systems, or sump pumps requires its own endorsement. During major flood events, both can happen at once — and you may need both coverages.
- It's risk-rated, and availability varies. Premiums depend on your flood risk, and homes in the highest-risk zones may face higher costs, higher deductibles, coverage limits, or may not qualify at all.
- Gradual seepage isn't covered by either. Slow leaks, chronic groundwater intrusion, and damage attributed to poor maintenance are generally excluded across the board — insurance is for sudden events, not deferred upkeep.
- Renters need their own protection. A landlord's policy won't cover a tenant's belongings damaged by overland flooding.
If you're not eligible for overland coverage or your loss isn't insurable, provincial Disaster Financial Assistance may be available after major declared events — but it's limited, and it's no substitute for proper coverage.
The documentation stakes are higher with floods
With any water loss, documentation matters. With overland flooding, it matters even more, because adjusters must establish exactly how and where water entered — and community-wide events mean claims volumes spike. Photograph everything before cleanup begins, keep damaged materials until your adjuster confirms they can go, maintain an inventory of damaged contents, and keep receipts for emergency expenses.
What Okanagan Property Owners Should Do Now
The 2017 and 2018 floods taught this valley that "record-breaking" can happen two years in a row. A few practical steps:
- Call your broker and ask two specific questions: "Do I have overland water coverage?" and "Do I have sewer backup coverage?" Don't assume — confirm, and get it in writing.
- Know your flood risk. The Okanagan Flood Story website, launched after the 2017–2018 events, offers interactive floodplain maps for the entire valley. Ten minutes on that map is time well spent.
- Manage the water on your own property. Grade soil away from your foundation, extend downspouts at least six feet from the house, keep gutters clear, seal foundation cracks, and consider a sump pump and backwater valve — measures that both reduce your risk and can help your insurability.
- Elevate what matters. Keep valuables, electronics, and irreplaceable items off basement floors, and raise appliances, furnaces, and hot water tanks where possible.
- Act fast when water strikes — whatever the source. Whether it's the lake at your door or a pipe in your wall, rapid professional response is the single biggest factor in limiting damage, cost, and disruption.
When Water Wins, We're Here
At Total Restoration Services, we've been helping North Okanagan, Shuswap, and Thompson families recover from water damage of every kind since 2002 — from freshet flooding to burst pipes and everything in between. Our emergency crews understand the difference between a clean-water loss and a contaminated flood loss, and we work directly with your insurer to make the claims process as smooth as possible.
If water has found its way into your home — from outside or in — call us 24/7. The valley's flood history tells us water will always find a way. Our job is to make sure your recovery does, too.
This article is for general information only and is not insurance advice. Coverage varies by insurer and policy — always confirm the details of your protection with your insurance broker or provider.